Global share markets endured their most bruising week in more than 18 months during the five trading sessions ended Friday, 20 November 2026, as an abrupt unwinding of the artificial intelligence (AI) trade collided with hawkish interest-rate warnings from the US Federal Reserve1. Wall Street tumbled into technical correction territory—led by a 10.0% weekly plunge in the Nasdaq Composite—after Anthropic’s record-breaking initial public offering (IPO) failed to steady sentiment and reports of a US regulatory accounting inquiry compounded a leadership crisis at Nvidia1. The sell-off rippled swiftly through Europe, Japan, Hong Kong, Taiwan, South Korea, and Australia, dragging the S&P/ASX 200 to its worst calendar week since early 20208.
Yet the week was defined as much by divergence as by risk aversion. While AI-exposed equity hubs shed trillions in market capitalisation, India staged a remarkable breakout, extending its winning streak to a fourth consecutive week as international funds rotated aggressively out of stretched technology shares and into Indian banks and blue chips12. Across the Tasman, New Zealand’s S&P/NZX 50 also displayed notable resilience, dipping just 0.5% after touching an all-time record high mid-week14. Meanwhile, commodity markets offered little shelter: gold dropped roughly 8% to 9% as US dollar strength weighed on bullion, copper sank into bear-market territory on AI-demand doubts, and crude oil notched a third straight weekly decline as Middle East tanker flows normalised16.
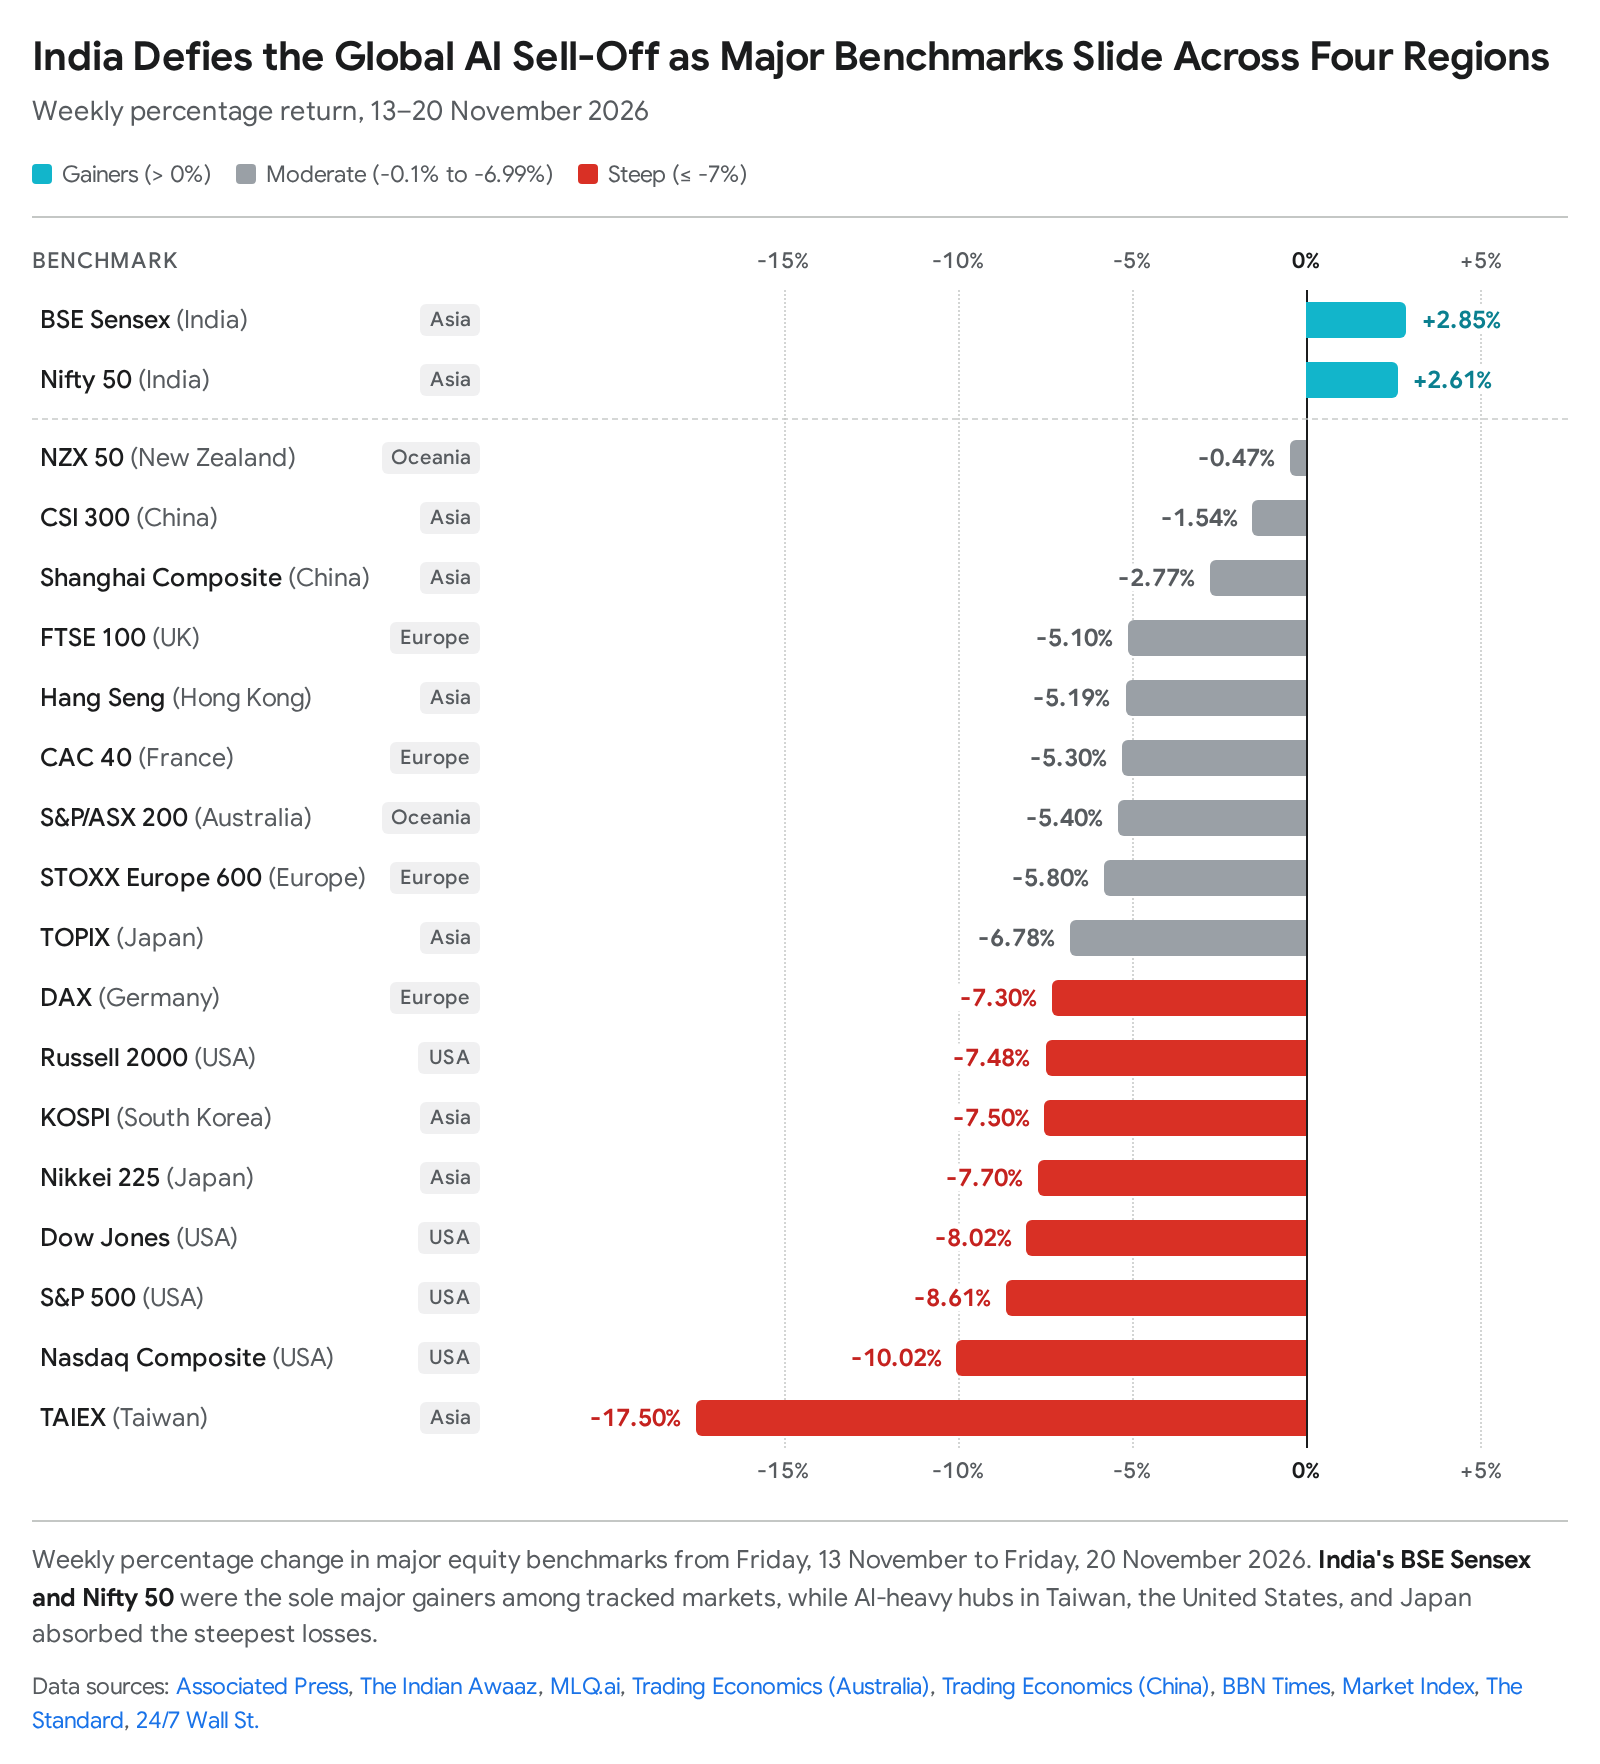
To provide an at-a-glance reference before examining each region in detail, the table below summarises the closing levels and weekly performance of key indices across the four regions covered in this review.
| Region | Benchmark Index | Friday Close (20 Nov 2026) | Friday Change | Weekly Change (13–20 Nov) |
| USA | S&P 500 | 6,910.39 | -3.70% | -8.61%1 |
| USA | Dow Jones Industrial Average | 48,147.33 | -1.93% | -8.02% |
| USA | Nasdaq Composite | 22,617.73 | -5.28% | -10.02% |
| USA | Russell 2000 | 2,581.79 | -2.8% | -7.48%1 |
| Europe | STOXX Europe 600 | 625.65 | -2.0% | -5.8%8 |
| Europe | DAX (Germany) | 24,802.78 | -2.6% | -7.3%1 |
| Europe | CAC 40 (France) | 7,927.75 | -1.9% | -5.3% |
| Europe | FTSE 100 (UK) | 10,346.34 | -1.0% | -5.1% |
| Asia | BSE Sensex (India) | 83,919.71 | +1.08% | +2.85%12 |
| Asia | Nifty 50 (India) | 25,800.60 | +1.12% | +2.61%22 |
| Asia | Nikkei 225 (Japan) | 56,436.65 | -5.06% | -7.70%15 |
| Asia | TOPIX (Japan) | 3,674.22 | -3.88% | -6.78%15 |
| Asia | Shanghai Composite (China) | 3,533.79 | -1.22% | -2.77%26 |
| Asia | CSI 300 (China) | 3,954.57 | -0.76% | -1.54%15 |
| Asia | Hang Seng Index (Hong Kong) | 22,410.80 | -1.89% | -5.19%28 |
| Oceania | S&P/ASX 200 (Australia) | 8,592.6 | -1.58% | -5.4%9 |
| Oceania | S&P/NZX 50 (New Zealand) | 14,107.41 | -0.98% | -0.47%14 |
United States: AI Unwind and Hawkish Fed Push Wall Street into Correction
Wall Street suffered its heaviest weekly sell-off in more than 18 months as a convergence of corporate shocks, stretched valuations, and interest-rate anxiety pushed all four major US stock benchmarks into technical correction territory—defined as a fall of at least 10% from recent highs1. By Friday’s closing bell, the S&P 500 had slipped below the 7,000 mark for the first time since April, shedding 651.28 points (-8.61%) over the week to settle at 6,910.391. The tech-heavy Nasdaq Composite bore the brunt of the downturn, tumbling 2,518.54 points (-10.02%) to 22,617.73—its steepest weekly fall since March 2020—which wiped out all of its 2026 gains to leave it down 2.7% year to date. The Dow Jones Industrial Average sank 4,200.22 points (-8.02%) to 48,147.33 in its fifth consecutive daily decline, while the small-cap Russell 2000 retreated 7.48% to 2,581.791.
Two major events in artificial intelligence triggered the wave of selling. First, AI lab Anthropic, maker of the Claude assistant, completed the largest IPO in US history on Thursday at USD 83 a share, raising roughly USD 81.3 billion and briefly commanding a valuation above USD 2 trillion4. Although shares initially surged to a peak of USD 115.10 and closed Thursday 17.1% above their offer price, the rally fizzled on Friday4. Anthropic retreated sharply during its second session—briefly dipping within five cents of its USD 83 offer price before bouncing to finish near USD 88.30 (down roughly 9% on the day, with intraday losses exceeding 10%)4. Rather than rekindling enthusiasm for AI, the mega-listing drained liquidity from competing technology stocks and sharpened scrutiny over whether record capital expenditure on data centres can deliver durable profits5.
Second, Nvidia endured a punishing sell-off even after reporting blockbuster third-quarter earnings on Tuesday—revenue more than doubled year on year to USD 115.84 billion and fourth-quarter guidance of USD 130 billion easily beat Wall Street estimates36. Investor confidence remained rattled following former CEO Jensen Huang’s resignation the prior week amid a personal-conduct controversy and board investigation, with Nvidia’s board chairman reiterating on Tuesday that the company has no plans to reinstate him under interim CEO Colette Kress6. Selling accelerated sharply on Friday after Reuters reported that US Securities and Exchange Commission (SEC) enforcement staff are examining potential accounting issues at the chipmaker—although market reports stressed that an SEC inquiry does not establish wrongdoing and many investigations close without enforcement action7. Nvidia closed down nearly 14% on Friday—its worst day since the January 2025 DeepSeek sell-off—bringing its drawdown from its 6 October record close to roughly 46% to 47% and erasing about USD 2.7 trillion in market value6. The broader Philadelphia Semiconductor Index slumped 10.73% on Friday, with Micron Technology (-13.9%) and AMD (-13.3%, also pressured earlier in the week by a short-seller report scrutinising its China ties) suffering heavy losses7.
Macroeconomic and political headwinds compounded the tech rout. Minutes from the Federal Reserve’s October meeting (released Wednesday) revealed near-unanimous support for further monetary tightening from the current 3.75%–4.00% target range, with a couple of officials floating an increase larger than 25 basis points in December if inflation persists3. Hawkish speeches throughout the week—including Fed Governor Christopher Waller advocating “aggressive action”, Governor Lisa Cook warning against falling “behind the curve”, and Philadelphia Fed President Anna Paulson signalling openness to back-to-back rate hikes—pushed markets to fully price in a 25-basis-point increase at the 8–9 December meeting3. Political uncertainty added another layer of caution: investors fretted that sweeping Democratic gains in the US midterm elections could herald tougher regulation on AI data-centre construction, while President Donald Trump threatened heavy taxes on companies building data centres offshore5.
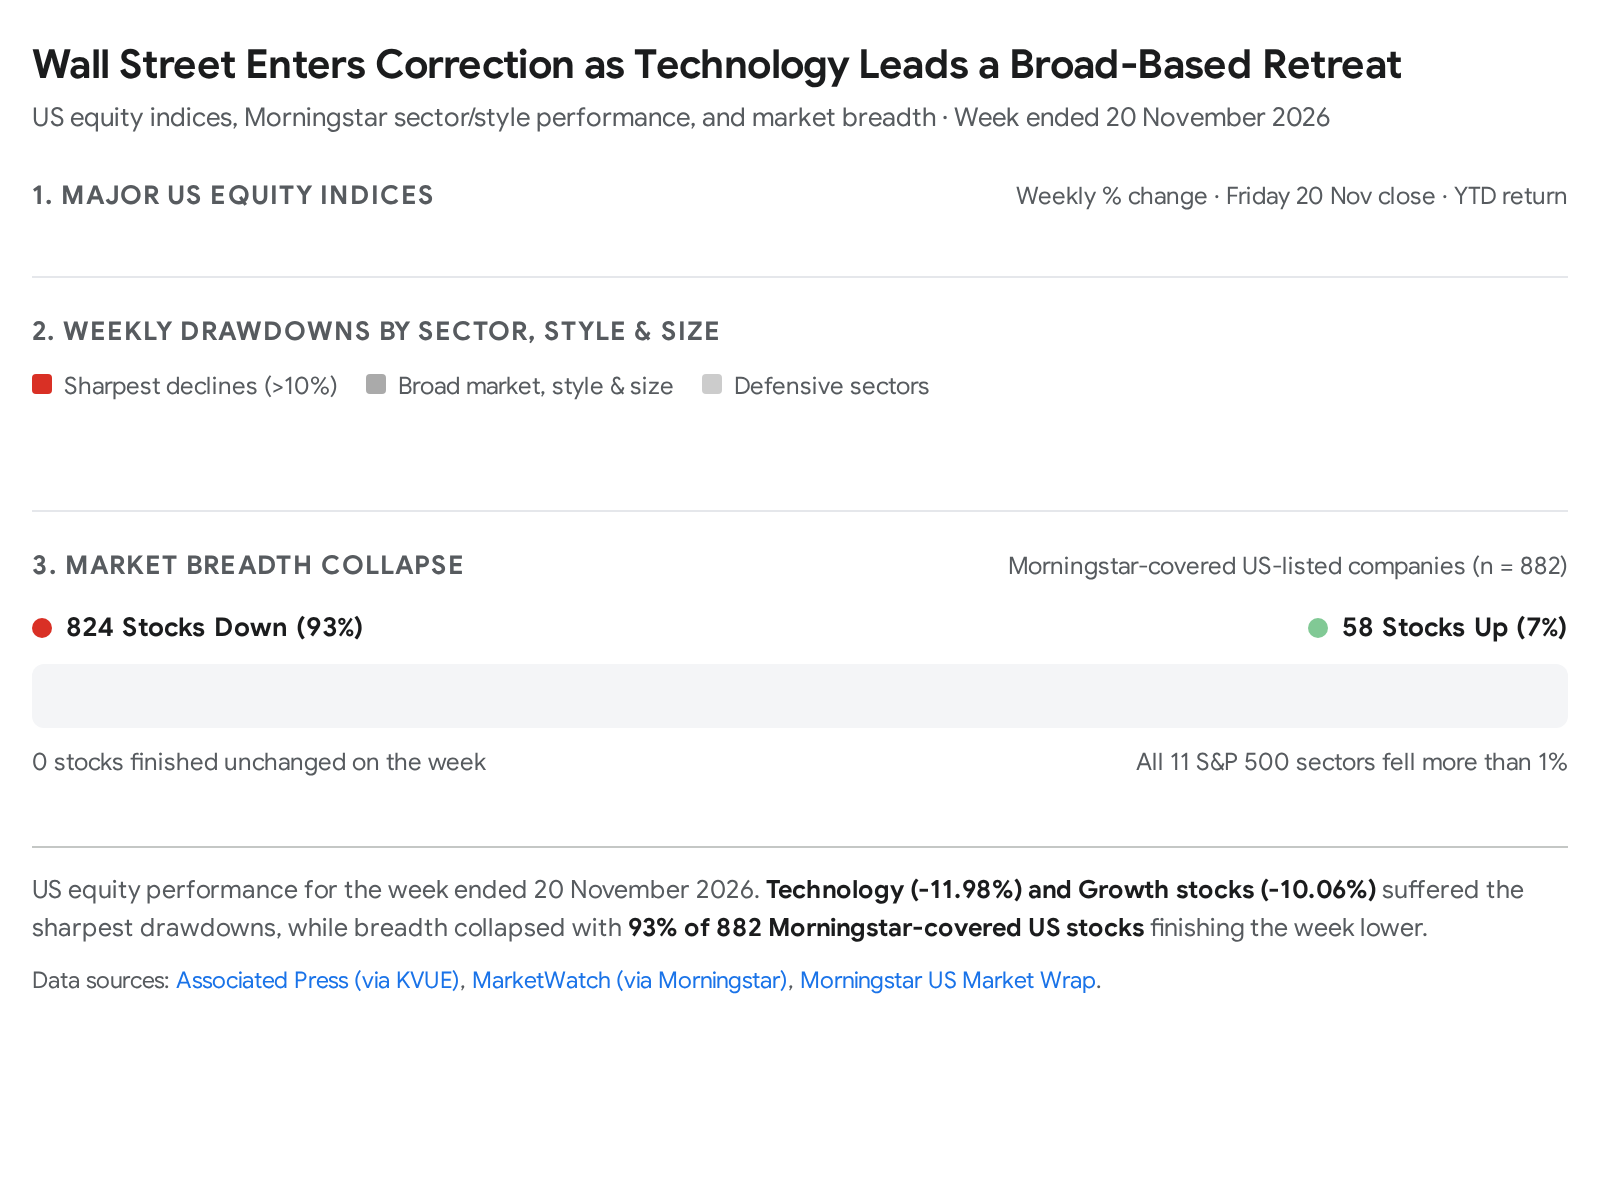
Across the broader market, all 11 S&P 500 sectors fell by more than 1% over the week, and 93% of the 882 US companies tracked by Morningstar ended in the red5. Defensive sectors such as consumer defensives (-2.03%) and utilities (-3.40%) cushioned losses, aided by resilient retail earnings from Walmart (which beat profit, revenue, and same-store sales expectations) and Lowe’s (which topped headline adjusted earnings estimates at USD 3.10 per share, though a 24/7 Wall St. analysis noted that stripping out a USD 0.34 per share tariff refund benefit would have left it below consensus)20. Safe-haven flows into US government bonds pulled the benchmark 10-year Treasury yield down from 5.15% to 4.92% by Friday, while the two-year yield eased from 4.88% to 4.63%20.
Europe: Chipmaker Slump, Banking Jitters and Geopolitical Shocks
European equities posted their steepest weekly decline since March, as the transatlantic AI reassessment collided with fresh geopolitical shocks and bank-specific governance concerns. The pan-European STOXX Europe 600 fell 2.0% on Friday to close at 625.65, capping a 5.8% weekly loss—though the benchmark still held a year-to-date gain of roughly 6% heading into Friday’s session. Germany’s DAX fared worst among Western European majors, logging a sixth straight daily drop (-2.6% on Friday to 24,802.78) to finish 7.3% lower for the week. France’s CAC 40 retreated 1.9% on Friday to 7,927.75 (-5.3% for the week), while London’s FTSE 100 shed 1.0% on Friday to 10,346.34 (-5.1% for the week), hitting a five-month low and recording its heaviest weekly loss since the outbreak of the Iran war.
Semiconductor and AI-infrastructure stocks spearheaded the European retreat, sending the regional technology index to its lowest point since May. On Friday alone, chipmakers STMicroelectronics (-9.1%), ASML (-8.7%), and Infineon (-7.9%) tumbled sharply, joined by power-equipment suppliers Siemens Energy (-6.6%), Legrand (-4.1%), and Schneider Electric (-3.5%), while property portal Scout24 slid 8% after a JPMorgan downgrade citing AI disruption risks. Financial stocks offered no refuge: Deutsche Bank dropped 3.2% on Friday to end 13% lower for the week after leaked whistleblower files revived concerns over compliance lapses, while Société Générale (-3.4%), ING (over -3%), BBVA (over -3%), and BNP Paribas (-2.4%) also retreated. In London, sliding copper and gold prices dragged resource heavyweights Antofagasta (-4.5%), Anglo American (-4.0%), Glencore (-2.6%), Endeavour Mining (-5.8%), and Fresnillo (-3.5%) lower. Industrial and defence majors—including Airbus, Rheinmetall, and Siemens (each down more than 4%)—alongside luxury houses Kering (-3.6%) and Hermès (-3.4%) also succumbed to widespread profit-taking.
Geopolitical and macroeconomic developments darkened the regional mood further. In Eastern Europe, Poland’s WIG30 sank 4.01% on Friday after Warsaw confirmed that two Russian missiles and a drone had crashed on Polish territory overnight during an attack on Ukraine. Meanwhile, official inflation data released on Wednesday highlighted Europe’s tricky policy backdrop. Eurostat confirmed Eurozone annual inflation hit a three-year high of 4.0% in October—double the European Central Bank’s (ECB) 2% target—fuelled by a 21.0% surge in energy costs stemming from the Middle East conflict, with core inflation edging up to 2.6%47. Even so, subdued economic growth led investors to bet the ECB would remain more cautious than the Federal Reserve48. In the United Kingdom, annual CPI rose to a one-year high of 3.6% in October on record diesel prices (199.5 pence per litre), edging slightly below some market forecasts of 3.7% while core inflation held steady at 2.8%36. Bank of England Governor Andrew Bailey noted that “monetary policy is not on a pre-set path”, dampening expectations of an imminent rate hike and weighing on the British pound, which also faced pressure from reported European Union frustration over UK–EU post-Brexit reset negotiations50. Amid the gloom, defensive European healthcare and consumer staples provided modest bright spots, with Unilever, AstraZeneca, Fresenius Medical Care (+2.4%), Hannover Re (+1.7%), and Sanofi (+1.3% on Bloomberg reports that it is weighing a €30 billion takeover of US drugmaker Insmed) finishing higher8.
Asia: A Tale of Two Markets as India Defies the Regional Tech Rout
Asian share markets experienced extreme bifurcation over the past seven days. MSCI’s broadest index of Asia-Pacific shares tracked its worst weekly decline since March 2020 as international funds fled the region’s AI hardware supply chain13. Outside the four focal economies detailed below, Taiwan’s TAIEX plunged 6.2% on Friday to 36,033.29—capping a staggering 17.5% weekly crash, its worst week since 1991—as contract chipmaking giant TSMC retreated, retail margin calls mounted, and regulators tightened short-selling limits10. South Korea’s KOSPI fell 5.21% on Friday to 4,869.96 (roughly -7.5% for the week), briefly triggering five-minute algorithmic selling curbs as memory giants Samsung Electronics (-7.0%) and SK Hynix (-5.9%) tumbled10. Against this backdrop of regional capitulation, India stood in stark contrast, absorbing billions in reallocated global capital to notch its fourth straight weekly advance12.
India: Banking Breakout and Record Foreign Inflows Power Four-Week Winning Streak
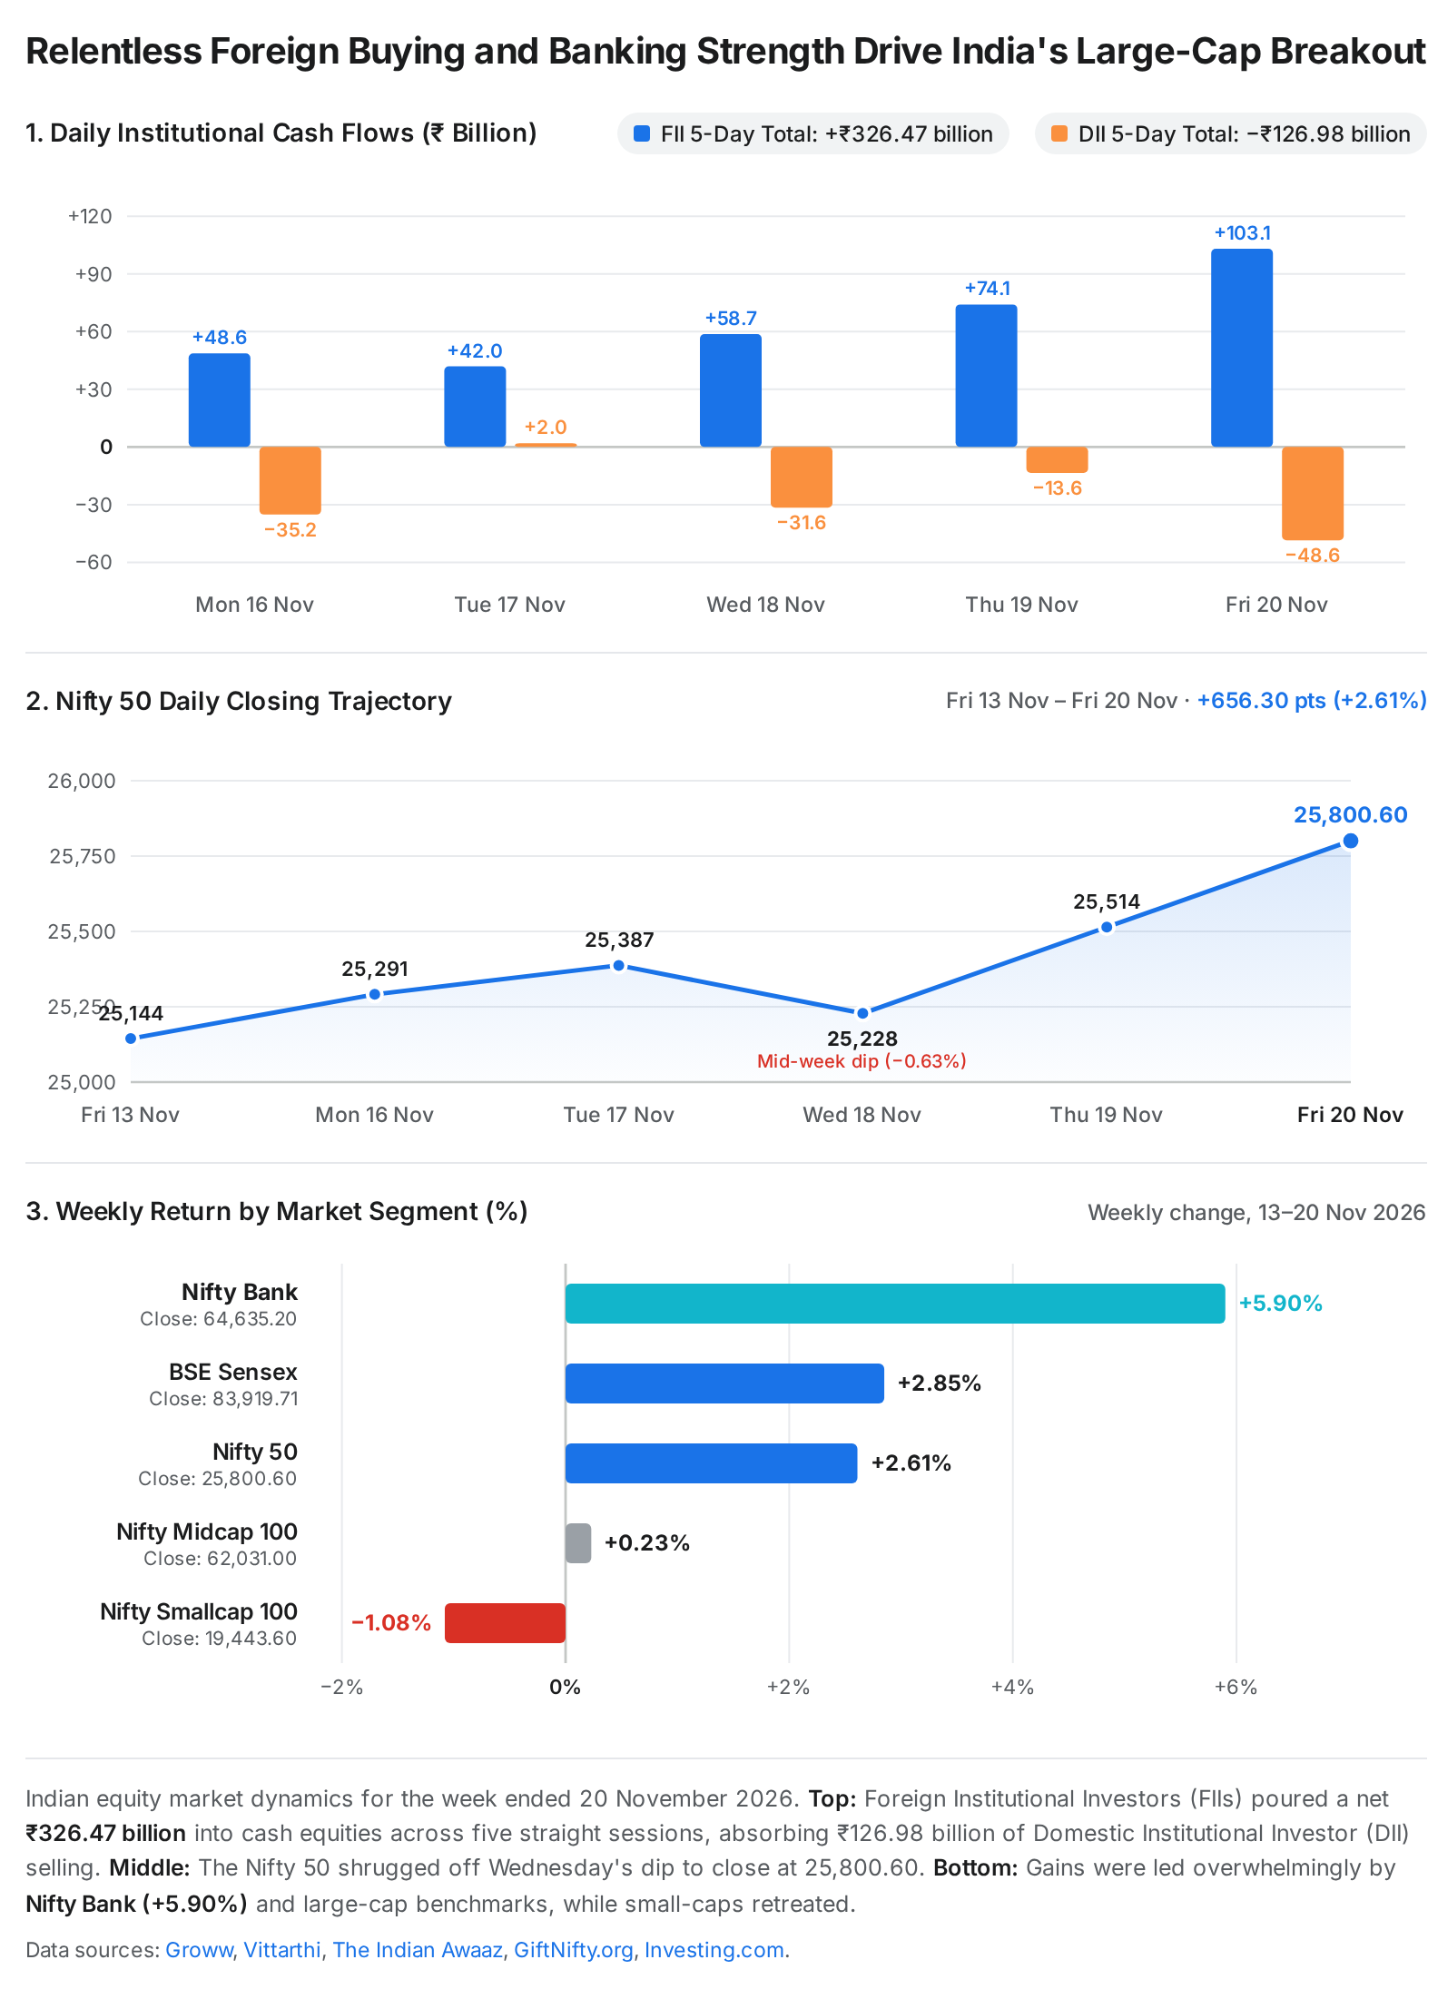
Indian equities delivered a standout display of resilience during the week ended 20 November 2026, shrugging off deepening global market turbulence to climb to nearly nine-month closing highs. The BSE Sensex rallied 897.96 points (+1.08%) on Friday to close at 83,919.71, securing a weekly advance of 2,327.26 points or +2.85% (up from 81,592.45 on 13 November). The NSE Nifty 50 mirrored that strength, jumping 286.30 points (+1.12%) on Friday to settle at 25,800.60—reclaiming the psychologically important 25,800 threshold for the first time since mid-February and finishing 656.30 points or +2.61% higher for the week12. Friday’s late surge alone added more than ₹2 trillion to investor wealth, lifting total BSE-listed market capitalisation to ₹514.15 trillion and NSE-listed capitalisation to ₹509.05 trillion (roughly USD 5.48 trillion)58.
The week’s session-by-session trajectory underscored the underlying bid for Indian blue chips. Both benchmarks started steadily on Monday (Nifty +0.58% to 25,291.10) and Tuesday (+0.38% to 25,387.40) on sustained overseas buying, before a mid-week bout of profit-taking and metal-stock weakness clipped the Nifty by 0.63% on Wednesday (to 25,227.95)61. Bulls swiftly regained control on Thursday—propelling the Sensex nearly 990 points higher (+1.21%) and the Nifty up 1.14% (to 25,514.30) as automobile shares rallied 3.52%61. Friday’s session encapsulated the entire week’s dynamic: after tumbling 250 to 350 points at the opening bell on grim Wall Street and Asian cues, domestic benchmarks staged a powerful intraday reversal to finish at their weekly highs12.
Foreign Inflows and the “Anti-AI” Rotation
The single biggest engine behind Dalal Street’s outperformance was a historic turnaround in overseas institutional demand. Global asset managers increasingly treated India as a defensive “anti-AI” trade: because Indian equity indices have limited direct exposure to AI hardware and data-centre capital expenditure, funds unwinding crowded positions in Taiwan (which saw roughly USD 20 billion in recent foreign outflows, according to market reports, and USD 56 billion across the quarter) and South Korea (roughly USD 8 billion to USD 9 billion in recent withdrawals, and USD 26 billion across the quarter) redeployed capital into Indian large-caps offering visible earnings and reasonable valuations12.
In the cash market, provisional exchange data showed Foreign Institutional Investors (FIIs) were net buyers on every single session of the week—injecting ₹48.65 billion on Monday, ₹41.95 billion on Tuesday, ₹58.67 billion on Wednesday, ₹74.11 billion on Thursday, and a massive ₹103.08 billion on Friday—bringing five-day net cash purchases to +₹326.47 billion and extending their unbroken buying streak to 15 straight sessions15. National Securities Depository Limited (NSDL) settlement data—which captures a slightly different weekly tally of ₹306.68 billion due to settlement timing and primary-market flows—confirmed that total foreign portfolio inflows for November so far have surged past ₹1,149.59 billion (roughly ₹1.15 trillion, including a record fortnightly intake of ₹842.91 billion in the first half of the month), making November 2026 one of the strongest monthly FPI inflow periods on record12. Conversely, Domestic Institutional Investors (DIIs) used the rally to book profits, net selling -₹126.98 billion in the cash market across the five sessions (with only Tuesday recording a modest net inflow of +₹1.97 billion)15.
Sectoral Leadership, Broader Market Divergence and Key Movers
The rally was unmistakably led by financials and banking, which absorbed over half of November’s record foreign inflows12. The Nifty Bank Index surged 5.90% over the week (climbing 3,601.10 points from 61,034.10 to close at 64,635.20) after scaling a fresh lifetime intraday peak of 64,680.80 on Friday12. Parallel benchmarks—including Nifty Private Bank (+3.01% on Friday), Nifty PSU Bank (+1.2% on Friday), Nifty Financial Services (+2.02% on Friday), and the BSE Bankex (+2.34% to 72,696.05)—all touched fresh record highs12. Investors flocked to private and state-owned lenders on resilient second-quarter earnings, stable asset quality, expectations of sustained credit growth, and attractive relative valuations (with Nifty Bank trading near a 13.9 times price-to-earnings ratio)12. On Friday alone, IndusInd Bank jumped 8.6%, Axis Bank gained 4.72%, HDFC Bank advanced 2.94%–3.02%, Kotak Mahindra Bank climbed 2.54%–3.08%, Bajaj Finance rose 2.67%, and ICICI Bank added 1.93%–2.22%61.
Information technology stocks also delivered a notable late-week reversal. After sliding for three straight sessions mid-week on US tech worries, the Nifty IT Index snapped back +1.30% on Friday (rising over 2% intraday) to 31,322.65, bucking the global tech slump23. Market analysts pointed to Indian IT outsourcers’ relatively asset-light business models, improving demand visibility, and renewed foreign interest, lifting Persistent Systems, Mphasis (+2.72%), TCS (+1.43%), Tech Mahindra (+1.35%), Infosys, and Wipro (+0.96%) on Friday—though mid-week weakness left the IT gauge lower for the full week (-2.61%)23. Elsewhere, Nifty Realty (+1.71% on Friday to a record high), hospital operators Apollo Hospitals (+5.29% on Friday, the top Nifty 50 gainer) and Max Healthcare (+3.88%), Maruti Suzuki (+3.11% on Friday following Thursday’s 3.52% auto rally), and UltraTech Cement (+3.02%) posted strong gains58.
On the downside, gains remained narrow and top-heavy. Across the broader market, investors favoured liquid large-caps while trimming smaller, higher-valuation counters12. Over the week, the Nifty Midcap 100 edged up just 0.23% (from 61,889.50 to 62,031.00), while the Nifty Smallcap 100 declined 1.08% (from 19,656.40 to 19,443.60)15. Market breadth remained negative even during Friday’s surge, with 2,456 declining stocks outnumbering 1,582 advancers on the BSE (and 2,205 decliners versus 1,414 advancers on the NSE)13. Meanwhile, India VIX climbed 7.51% on Friday to 17.32 (up from 15.50 a week earlier), signalling heightened caution beneath the surface61. Sectoral laggards included Nifty Metal (-2.5% Wednesday, -0.23% Friday; Tata Steel -1.60% and Vedanta -2.32% on Friday) due to falling global base-metal prices, Nifty Media (-1.68% Friday), and Consumer Durables—where a steep drop in domestic gold (-3.38% Friday on the MCX to ₹123,150 per 10 grams) and silver (-3.89%) weighed on jewellery counters such as Titan Company (-1.70% Friday, the worst Nifty 50 performer)59.
Macroeconomic Cross-Currents, the Rupee and Primary Market Activity
India’s equity rally unfolded against a complex macroeconomic backdrop combining currency strength and booming industrial output with stubborn inflation pressures:
| Indian Economic / Market Indicator | Latest Reading (as of 20 Nov 2026) | Prior Reading / Context | Market Implication |
| USD/INR Exchange Rate | ₹92.64–92.67 per USD | ₹94.24 (13 Nov) | +1.67% weekly rupee gain; 7-month high on FPI inflows and softer oil12 |
| Core Infrastructure Output (Oct) | +10.9% YoY | +8.2% (Sep) | Fastest pace under new 2022–23 series; led by iron ore (+26.4%), coal (+23.1%), electricity (+21.6%)84 |
| Wholesale Price Inflation — WPI (Oct) | 12.29% YoY | 11.39% (Sep) | Series high driven by 32.84% fuel & power jump; margin-pressure risk86 |
| Retail Inflation — CPI (Oct) | 6.09% YoY | 5.54% (Sep) | Breached RBI’s 6% upper tolerance ceiling; food inflation at 8.94%89 |
| RBI Policy Repo Rate | 5.50% | Raised +25 bps in Oct | Negative real rate puts focus on 2–4 December MPC meeting88 |
| Unemployment Rate (Oct) | 4.9% | 5.0% (Sep) | Eight-month low, signalling resilient domestic labour demand82 |
Two external tailwinds proved pivotal. First, Brent crude oil traded near USD 90 to USD 92 per barrel—roughly 20% below its late-October peak near USD 118—offering substantial relief to India’s oil-import bill, current account deficit, and corporate margins in aviation, paints, chemicals, and logistics12. Second, heavy foreign equity inflows helped the Indian rupee strengthen past the 93-per-dollar threshold for the first time since April, posting its best weekly advance in five weeks despite broad US dollar strength globally12.
However, inflation remains a critical test ahead of the Reserve Bank of India’s (RBI) 2–4 December Monetary Policy Committee (MPC) meeting89. Following last week’s shock retail CPI reading of 6.09% (above the RBI’s 2%–6% mandate), official provisional data published Monday revealed that Wholesale Price Index (WPI) inflation accelerated to a new-series peak of 12.29% in October—more than double the retail rate—driven by surging crude petroleum (+70.80%) and mineral oil (+45.57%) prices prior to November’s crude pullback88. On the growth side, Friday’s surge of 10.9% in October’s nine core infrastructure sectors pointed to brisk industrial momentum, though ICRA Chief Economist Aditi Nayar cautioned that a low year-ago base (+0.8% in October 2025 due to festive-calendar shifts) flattered the headline pace and predicted growth would cool to mid-single digits in November84. Economists remain divided on whether the RBI will deliver another 25-basis-point rate rise in December under its “calibrated tightening” stance or pause to assess November’s lower energy costs83.
Finally, India’s primary and index-rebalancing calendars remained vibrant despite global volatility. The ₹4.55 billion mainboard IPO of Crystal Crop Protection (priced at ₹259–272) closed on Friday with strong 17.1 to 17.7 times overall subscription—led by non-institutional bidders at roughly 38–39 times and institutional buyers at 15–16 times—ahead of its 26 November listing96. State-owned coal producer Mahanadi Coalfields opened its landmark ₹89.81 billion mainboard IPO (₹129–136 band) on Thursday; by the close of Day 2 on Friday, overall bids stood at 0.48 to 0.49 times, with qualified institutional buyers already subscribing 1.37 times ahead of Monday’s close99. In the SME segment, Watrana Rentals (₹1.20 billion) drew over 11 times subscription by Day 224. Meanwhile, BSE announced its latest index rejig, with Shriram Finance set to replace Trent in the Sensex, and Vedanta Aluminium and MCX joining the BSE 100100.
Japan: Nikkei Plunges into Bear Market Ahead of Holiday Weekend
Japanese equities suffered a dramatic reversal, culminating in Friday’s steep sell-off as investors shed AI-exposed holdings ahead of a three-day holiday weekend in Tokyo101. The benchmark Nikkei 225 tumbled 3,007.56 points (-5.06%) on Friday to close at 56,436.65—the fifth-largest single-day point drop in the index’s history and its lowest close in roughly seven-and-a-half months24. Across the week, the Nikkei shed 4,705.70 points (-7.70%) from its 13 November close of 61,142.35, leaving it roughly 22% to 23% below its June 2026 record peak (72,353.96) and officially in bear-market territory10. The broader TOPIX index fell 3.88% on Friday to 3,674.22, losing 6.78% over the week, with roughly 90% of Tokyo Stock Exchange Prime Market shares declining early in Friday’s session15.
Although Tokyo briefly stabilised mid-week—notching small gains on Wednesday (+0.28%) and Thursday (+0.71%) after October exports surprised on the upside with a 20.5% annual jump—Friday’s rout was swift and concentrated in AI bellwethers99. SoftBank Group crashed 14.48%—its worst session since August 2024—on global tech liquidations affecting its major stakes in OpenAI and Arm, while chip-testing equipment maker Advantest (-10.32%), Tokyo Electron (-7.06%), memory maker Kioxia (-11.7%), and cable supplier Fujikura (-12.2%) dragged the Nikkei steeply lower10.
Domestic economic data painted a delicate picture for the Bank of Japan (BoJ) ahead of its December policy meeting. Preliminary Cabinet Office figures released Monday showed Japan’s economy unexpectedly contracted 0.02% quarter on quarter (-0.1% annualised) in the July–September quarter—its first contraction in four quarters—while October’s trade balance logged a sixth consecutive monthly deficit (¥476.5 billion) due to elevated energy import costs106. On Friday, October national consumer price inflation missed consensus estimates across all three main gauges, yet headline inflation still quickened to an 11-month high of 2.3% (from 2.1%) and core CPI ticked up to 2.2%24. Because underlying inflation remains above the BoJ’s 2% target, markets continued to price in a potential December rate rise from the current 1.25% policy rate24. The Japanese yen, which had hovered perilously near 160 per US dollar earlier in the week amid official intervention warnings, firmed as a safe haven toward 158.5 to 159 per US dollar on Friday as equity risk appetite evaporated26.
China: Mainland Benchmarks Edge Lower as PBOC Holds Lending Rates
Mainland Chinese equities fared better than most global peers during the week’s turmoil, though losses in domestic technology shares still kept benchmarks under pressure inside an ongoing bear market54. The Shanghai Composite declined 1.22% on Friday to close at 3,533.79, taking its weekly decline to 2.77%1. The large-cap CSI 300 slipped 0.76% on Friday to 3,954.57, finishing 1.54% lower over the five sessions and hovering near 16-month lows roughly 20% below its June peak15. Growth and tech-focused mainland gauges absorbed heavier selling: the Shenzhen Component fell 3.09% on Friday to 10,256.39 (-6.49% for the week), while the ChiNext (-3.54%) and STAR 50 (-3.12%) also ended Friday sharply lower1.
Sentiment was weighed down early in the week by soft October economic indicators showing industrial production slowing to 4.8% year on year (missing the 5.3% forecast), retail sales decelerating sharply to 0.4% (versus 0.8% expected), fixed-asset investment contracting 8.1% year to date, and new home prices continuing to edge lower113. Despite the sluggish domestic momentum, the People’s Bank of China (PBOC) left its benchmark Loan Prime Rates (LPR) unchanged on Friday for an 18th consecutive month—holding the one-year LPR at 3.0% and the five-year mortgage reference rate at 3.5%114. Stronger-than-expected third-quarter GDP growth of 4.5% and a firmer yuan (near 6.68 per US dollar) reduced immediate urgency for fresh rate cuts, even as the central bank reiterated its commitment to an “appropriately loose” stance26. On the corporate front, mainland semiconductor and biotech names—including Hygon Information Technology (-8.75%), Zhongji Innolight (-3.72%), WuXi AppTec (-2.49%), and NAURA Technology (-2.20%)—led Friday’s declines, while state-owned giants PetroChina (+4.67%), ICBC (+3.30%), Bank of China (+2.72%), and Kweichow Moutai (+1.75%) helped cushion the Shanghai benchmark26.
Hong Kong: Hang Seng Enters Bear Market Amid Tech Capex Concerns
Hong Kong stocks crossed a sombre technical threshold on Friday as global AI jitters merged with investor unease over domestic tech giants’ ballooning capital expenditure and mixed quarterly earnings29. The flagship Hang Seng Index (HSI) dropped 430.82 points (-1.89%) on Friday to close at 22,410.80—its fourth straight daily loss, its lowest finish since April 2025, and a 5.19% weekly decline34. During Friday’s session, the index touched a 52-week intraday low of 22,307.42, extending its fall from its 29 January 2026 high to 20% and officially placing it in bear-market territory28. The Hang Seng Tech Index (HSTECH) fared even worse, tumbling 3.78% on Friday to 3,511.14 (briefly breaching 3,500) to mark its eighth consecutive daily decline and a near two-year low28.
Quarterly results from Chinese internet leaders drew sharp scrutiny over cash flow quality. Tencent’s third-quarter capital expenditure jumped 527% year on year to CNY 81.43 billion—turning free cash flow negative at CNY 69.1 billion—while earnings missed market forecasts33. On Friday, gaming giant NetEase plunged 17.60% after reporting declines in both third-quarter revenue and profit, short-video platform Kuaishou fell 11.37%, and Hua Hong Semiconductor lost 10.17%, while financial heavyweights HSBC Holdings (-3.3%) and Ping An Insurance (-2.0%) added to the drag29. Alibaba stood out as a rare bright spot on Friday, rising 3.48% after posting a 213% surge in net profit despite its own heavy AI capital outlays (CNY 50.48 billion) pushing cash flow into negative territory29.
Even amid the sell-off, mainland Chinese investors stepped in to buy the dip via Stock Connect, channelling HKD 11.81 billion in net southbound inflows on Friday29. Looking ahead, Hang Seng Indexes Company announced a landmark quarterly index overhaul after Friday’s close: effective 7 December, the Hang Seng Tech Index will expand from 30 to 50 constituents for the first time, adding 20 hardware, AI, and robotics names—including battery powerhouse CATL (carrying the largest new weight at 2.17%), Luxshare Precision, Zhongji Innolight, Hesai, and UBTech—a reshuffle Huatai Securities estimates could generate roughly HKD 29 billion in passive rebalancing flows119.
Oceania: ASX Suffers Worst Week Since 2020 While New Zealand Holds Firm
Equities across Oceania traced markedly different paths over the past seven days. Australia’s resource- and bank-heavy sharemarket was caught squarely in the crossfire of the global tech unwind, tumbling metal prices, and domestic labour-market nerves, whereas New Zealand’s defensive, yield-oriented bourse hovered near all-time highs before succumbing to mild late-week profit-taking9.
Australia
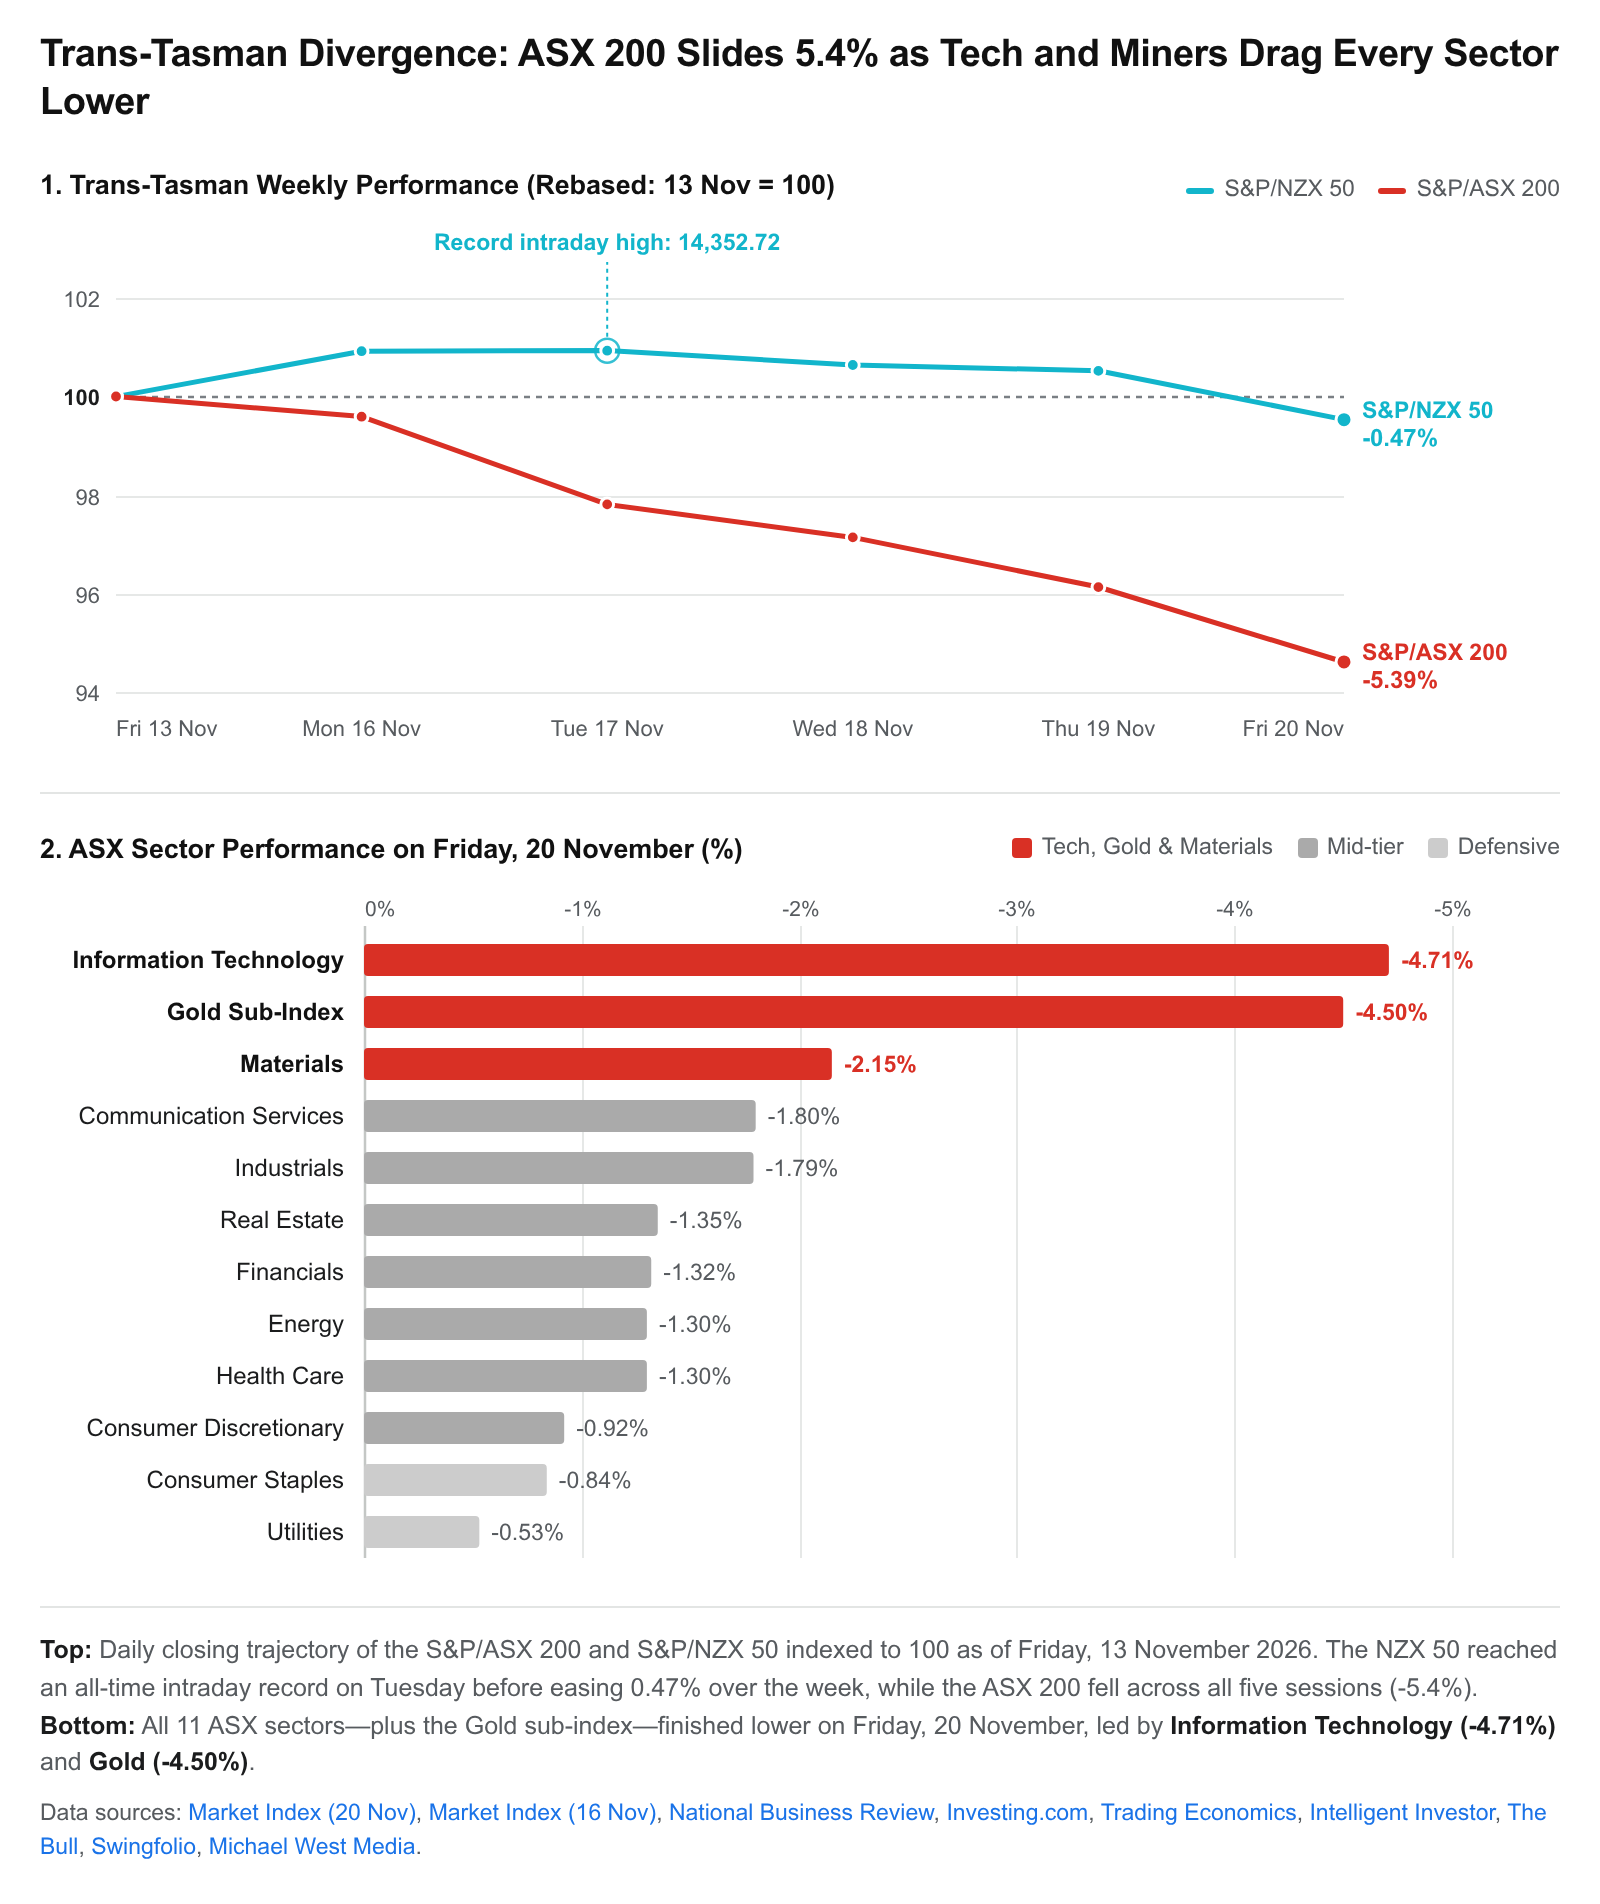
The S&P/ASX 200 suffered its worst calendar week since early 2020, falling 137.8 points (-1.58%) on Friday to close at 8,592.6—a five-month low that extended the benchmark’s losing streak to seven consecutive sessions9. Over the five trading days, the ASX 200 tumbled 490 points (-5.4%), slicing decisively below the psychological 9,000 level on Tuesday and erasing gains built over the prior three weeks30. The broader All Ordinaries dropped 143.8 points (-1.63%) on Friday to 8,692.8 (-5.56% for the week), while the Small Ordinaries slid 2.71% on Friday to 2,971.39.
Every one of the ASX’s 11 sectors finished in the red on Friday31. Local Information Technology (-4.71% on Friday) was the hardest-hit sector, mirroring Wall Street’s AI unwind: Megaport plunged 12.9% (compounded by a first remuneration-report strike at its AGM), Appen fell 9.5%, Life360 slid 7.2%, data-centre operator NEXTDC dropped 7.1% despite upgrading revenue and earnings guidance, Xero shed 5.7%, and WiseTech Global lost 3.8%31.
Materials (-2.15% on Friday; down roughly 15% since 12 November) and the Gold sub-index (-4.5% on Friday) were hammered by collapsing commodity prices and soft Chinese industrial data31. With copper plunging into bear-market territory on AI-spending doubts and iron ore slipping below USD 90 a tonne earlier in the week (near a four-year low on swelling Chinese port inventories and rising supply from Guinea’s Simandou mine), mining giant BHP Group fell 1.8% on Friday to AUD 51.40—completing a roughly 13% weekly tumble to a seven-month low30. Because copper now generates 54% of BHP’s underlying EBITDA, the metal’s sell-off hit the miner acutely, allowing Commonwealth Bank to reclaim its position as the ASX’s largest company by market capitalisation124. Gold producers (Genesis Minerals -5.8%, Capricorn Metals -5.1%), copper miners (Aeris Resources -7.5%, Sandfire Resources -3.6%), critical-minerals developers, and uranium stocks (Silex Systems -7.9%, Deep Yellow -7.4%, Boss Energy -6.4%, Paladin Energy -5.5%) were heavily sold, though pure-play iron ore miners Fortescue (+2.1% to AUD 13.44) and Champion Iron (+0.9%) bucked Friday’s gloom on a modest bounce in Singapore futures. Financials (-1.32% on Friday) also retreated, with all four major banks lower—led by Westpac (-2.23%), NAB (-1.31%), ANZ (-1.08%), and CBA (-1.00% to AUD 169.92)—alongside Macquarie Group (-2.17%) and Zip Co (-9.4%)30. Defensive Utilities (-0.53%) and Consumer Staples (-0.84%) offered the best relative shelter.
Domestic economic releases kept investors on edge over the Reserve Bank of Australia’s (RBA) policy path after five interest-rate hikes in 2026 lifted the cash rate to 4.85% to combat sticky inflation (4.3% in September)30. Wednesday’s September-quarter Wage Price Index came in firm at 1.1% quarter on quarter (3.5% annually, the fastest quarterly clip since December 2023), keeping inflation worries alive127. Yet Thursday’s October labour force report revealed the unemployment rate jumped to a five-year high of 4.9%, fuelling economic-slowdown fears while simultaneously tempering bets on further RBA rate rises ahead of next week’s October inflation print30. Souring global risk appetite pushed the Australian dollar down to 66.67 US cents on Friday afternoon (easing toward 66.2 cents in late offshore trade), well off the 72 US cents mark seen in September9.
New Zealand
Across the Tasman, New Zealand’s S&P/NZX 50 demonstrated impressive stability amid the global sell-off. Supported early in the week by utilities and consumer discretionary stocks, the benchmark climbed to a record intraday high of 14,352.72 on Tuesday14. Global tech nerves and local profit-taking eventually caught up over the final three sessions, dragging the index down 139.84 points (-0.98%) on Friday to close at 14,107.4114. Even so, the NZX 50 finished the week down a modest 0.47% (-0.5%), snapping a three-week winning streak with 34 constituents declining, 15 rising, and Spark New Zealand unchanged.
Corporate news drove sharp single-stock moves. Dairy exporter a2 Milk weighed heavily on consumer staples, plunging 9.2% on Thursday after warning on first-half FY27 earnings and shedding another 2.3% on Friday128. Logistics and infrastructure stocks Freightways (-2.7%), Mainfreight (-2.1%), and Infratil (-1.7%) also softened on Friday, whereas Auckland International Airport (+0.9%) and Turners Automotive (+0.7% after reporting a 4% rise in first-half FY27 net profit) bucked the downward drift.
On the policy front, the Reserve Bank of New Zealand’s (RBNZ) latest Financial Stability Report flagged elevated global risks from Middle East energy disruptions, high bond yields, and stretched AI equity valuations130. Meanwhile, the RBNZ’s fourth-quarter inflation-expectations survey released Tuesday delivered a mixed message: one-year expectations jumped to 2.92% (from 2.60%) and two-year expectations edged up to 2.36% (from 2.34%), while five-year expectations eased to 2.17%131. With annual inflation sitting at 3.7% in the September quarter (and projected by the RBNZ to reach 4.4% in the December quarter on fuel costs) and Governor Anna Breman warning of indirect fuel-price pass-through, swap markets heavily priced in a 25-basis-point lift in the Official Cash Rate from 2.75% to 3.00% at the central bank’s 9 December review130. The New Zealand dollar slipped 0.5% over the week to 54.91 US cents, though it gained 1.1% against the Australian dollar to trade at 82.41 Australian cents14.
Conclusion
The week ended 20 November 2026 marked a significant inflection point for global financial markets. For months, equity gains across the United States, Europe, and North Asia had rested heavily on two pillars: strong optimism surrounding artificial intelligence spending and hopes that central banks were finished tightening. Over the past seven days, both pillars came under intense strain simultaneously3. Anthropic’s muted post-IPO follow-through, Nvidia’s leadership turmoil and reported SEC accounting inquiry, and soaring capital outlays at Chinese tech giants prompted investors to pivot abruptly from rewarding raw AI growth toward scrutinising cash flows, governance, and return on investment6. At the same time, stubborn inflation across the US, Europe, Japan, Australia, New Zealand, and India reminded markets that borrowing costs are likely to stay restrictive for longer3.
Crucially, however, capital did not merely retreat to cash and government bonds—it rotated. India’s four-week winning streak, powered by over ₹326 billion in weekly foreign cash buying and record highs across banking indices, highlighted the growing appeal of domestically driven, lower-AI-exposure markets when mega-cap tech falters12. Heading into the final week of November, investors face a packed calendar of catalysts—including the US Personal Consumption Expenditures (PCE) inflation gauge, third-quarter US GDP figures, Australia’s October inflation report, and New Zealand retail sales—all of which will shape central-bank policy decisions across December and test whether battered global tech and resource stocks can find a durable floor3.
Disclaimer
The information contained in this article is provided strictly for general informational and educational purposes only and does not constitute personal financial, investment, legal, or taxation advice. It has been prepared without taking into account your individual financial objectives, personal circumstances, or risk tolerance. Stock markets, currencies, and commodities are inherently volatile, and asset values can fall as well as rise; past performance is never a reliable indicator of future results. While reasonable care has been taken to ensure the accuracy of market figures and commentary sourced from publicly available reports as at 21 November 2026, no guarantee is made regarding completeness or timeliness. Before making any investment or trading decision, you should conduct your own independent research and consult a qualified, licensed financial adviser.
References
- How major US stock indexes fared Friday 11/20/2026, https://www.kvue.com/article/syndication/associatedpress/how-major-us-stock-indexes-fared-friday-11202026/616-ddb71432-40dc-428c-97d9-7f706955d9e8
- Anthropic’s stock surges in its debut – and the rest of the market, https://www.morningstar.com/news/marketwatch/20261120123/anthropics-stock-surges-in-its-debut-and-the-rest-of-the-market-dives-anyway
- Fed signals and data: what happened the week of Nov. 16–20, 2026, https://www.investing.com/news/stock-market-news/fed-signals-and-data-what-happened-the-week-of-nov-1620-2026-93CH-5042523
- US stocks tumble, and the S&P 500 drops as the sell-off for AI stocks, https://www.ksat.com/business/2026/11/20/asia-shares-drop-on-ai-worries-echoing-wall-streets-decline-despite-the-strong-anthropic-debut/
- Dow, S&P 500 enter correction as Nasdaq suffers worst week since, https://www.morningstar.com/news/marketwatch/20261120431/dow-sp-500-enter-correction-as-nasdaq-suffers-worst-week-since-2020
- SEC Is Investigating Nvidia’s Accounting Practices, According To Report, https://www.forbes.com/sites/fionariley/2026/11/20/sec-is-investigating-nvidias-accounting-practices-according-to-report/
- Nvidia Stock Plunges 12% After Reuters Reports an SEC Probe of, https://247wallst.com/investing/2026/11/20/nvidia-stock-plunges-12-after-reuters-reports-an-sec-probe-of-its-accounting-its-nvidias-worst-day-since-deepseek-and-it-has-lost-2-7-trillion-since-october/
- European stocks close down 2% to cap their worst week since, https://mlq.ai/news/european-stocks-close-down-2-to-cap-their-worst-week-since-march-as-asml-and-infineon-slump/
- Grim week wipes billions from Australian share market – Michael West, https://michaelwest.com.au/aussie-share-market-on-track-for-worst-week-in-years/
- Taiwan Stock Market Falls 6.2% to Cap Its Worst Week Since 1991, https://247wallst.com/investing/2026/11/20/taiwan-stock-market-falls-6-2-to-cap-its-worst-week-since-1991-as-kospi-closes-down-5-2-and-nikkei-225-drops-5-1-in-ai-chip-selloff/
- Asian stocks close sharply lower as Taiwan falls 6% and the Nikkei, https://mlq.ai/news/asian-stocks-fall-at-the-open-on-friday-nov-20-as-the-nikkei-drops-more-than-4-after-anthropics-debut/
- Stock Market Weekly Round-Up (16-20 November 2026), https://theindianawaaz.com/stock-market-weekly-round-up-16-20-november-2026/
- Sensex Surges 898 Points; Nifty Reclaims 25,800 Mark, https://hdfcsky.com/news/market-close-report-today-november-20-2026-nifty-sensex-scale-nine-month-highs-as-investors-dump-global-ai-for-india
- NZX 50 retreats from record, snapping three weeks of gains – NBR, https://www.nbr.co.nz/market-close/nzx-50-retreats-from-record-snapping-three-weeks-of-gains/
- unknown_url
- Morning Wrap: ASX 200 to fall, S&P 500 extends losing streak, Anthropic makes record debut, https://www.marketindex.com.au/news/morning-wrap-asx-200-to-fall-s-and-p-500-extends-losing-streak-anthropic
- Oil prices set for third straight weekly decline on strong Middle East, https://www.lse.co.uk/news/oil-prices-set-for-third-straight-weekly-decline-on-middle-east-export-flows-qp84b5zsu0mheqd.html
- Gold price heads for worst weekly loss since March, https://mining.com.au/gold-price-heads-for-worst-weekly-loss-since-march/
- Copper price sinks into bear market, erasing 2026 gains in worst, https://www.mining.com/copper-price-sinks-into-bear-market-erasing-2026-gains-in-worst-week-of-the-year/
- https://www.morningstar.com/markets/market-wrap-stocks-lose-851-technology-basic-materials-fall
- Nasdaq Plunges 5%, Erasing All Year-to-Date Gains; Nvidia Tumbles 13% as AI Stock Selloff Deepens, https://www.tradingkey.com/analysis/stocks/us-stocks/262316111-nasdaq-falls-ai-stock-selloff-nvidia-sec-probe-tradingkey
- Dow Jones Industrial Average drops for a fifth day as AI rout widens, https://www.mitrade.com/au/insights/news/live-news/article-4-2269081-20261121
- Infosys, TCS, HCL Tech: Indian IT stocks buck global AI rout trend; Nifty IT jumps 2% – Key reasons | Top shares to buy, https://www.livemint.com/market/stock-market-news/infosys-tcs-hcl-tech-indian-it-stocks-buck-global-ai-rout-trend-nifty-it-jumps-2-key-reasons-top-shares-to-buy-11795103694291.html
- Nikkei 225 Crashes to 56,436.65 as SoftBank and Advantest Lead the AI Rout, https://www.bbntimes.com/companies/nikkei-225-crashes-to-56-436-65-as-softbank-and-advantest-lead-the-ai-rout
- Japan’s Nikkei plunges over 5 pct on AI concerns, https://english.news.cn/20261120/ae932d698b7e4353adc0d8aa3a6d004f/c.html
- China Shanghai Composite Stock Market Index – Trading Economics, https://tradingeconomics.com/china/stock-market
- On Friday, November 20, China’s Shanghai Comp, https://news.futunn.com/en/flash/1005147842/on-friday-november-20-china-s-shanghai-composite-index-closed
- Hong Kong Stock Exchange: Hang Seng Index Slides to 22,410.80 Amid US-Iran Negotiations, https://www.bbntimes.com/financial/hong-kong-stock-exchange-hang-seng-index-slides-to-22-410-80-amid-us-iran-negotiations
- Hong Kong Stocks Plunge on “Black Friday”: Hang Seng Index Sinks 430 Points for Fourth Straight Loss as NetEase Craters 17% After Earnings, https://finance.biggo.com/news/9af34c66-ec95-4b77-b304-b7071ecb93b7
- Australia Stock Market Index – Quote – Chart – Historical Data – News, https://tradingeconomics.com/australia/stock-market
- Evening Wrap: ASX 200 cops a 490-point weekly drubbing as AI trade unwind, growth fears crush stocks, https://www.marketindex.com.au/news/evening-wrap-asx-200-cops-a-490-point-weekly-drubbing-as-ai-trade-unwind
- New Zealand Stock Market (NZX 50) – Quote – Chart – Historical Data, https://tradingeconomics.com/new-zealand/stock-market
- AI Spending Burns Too Hot! Hang Seng Tech Index Plunges Another 4% to Near Two-Year Low, https://finance.biggo.com/news/5e51ad0d-c804-4e45-84ac-3d294fdbeffd
- Market Quick Take – Asian stocks tumble after Wall Streets sixth straight decline – 20 November 2026, https://www.home.saxo/en-mena/content/articles/macro/market-quick-take—asian-stocks-tumble-after-wall-streets-sixth-straight-decline—20-november-2026-20112026
- AI Bubble Fears Explode: Nasdaq Plunges Over 5% in a Single Day, Nvidia Sinks 14% to 52-Week Low, https://finance.biggo.com/news/9e27194c-6fae-464b-87ea-606ff5a4d45d
- UK inflation rises to highest level in a year on back of higher petrol and diesel prices – as it happened, https://www.theguardian.com/business/live/2026/nov/18/uk-inflation-rises-higher-petrol-prices-nvidia-live-updates
- Nvidia falls after SEC probe on potential accounting issues, https://investinglive.com/stocks/nvidia-down-falls-after-sec-probe-on-potential-accounting-issues/
- Nvidia Stock Plunge Wipes Out Nearly $500 Billion in One Day as SEC Reportedly Probes Its Accounting, https://www.fool.com/investing/2026/11/20/nvidia-stock-plunge-wipes-out-nearly-usd500-billion-in-one-day-as-sec-reportedly-probes-its-accounting/
- Nvidia shares fall 11.5% as report of SEC accounting probe adds to, https://au.investing.com/news/stock-market-news/nvidia-shares-fall-115-as-report-of-sec-accounting-probe-adds-to-pressure-4787315
- US 10-year Treasury yield slips below 5% as global equity rout deepens, https://www.mitrade.com/au/insights/news/live-news/article-6-2268250-20261120
- How the US Fed’s rate hike hits your stocks, bonds, gold and silver investments, https://www.financialexpress.com/market/global-markets/how-the-us-feds-rate-hike-hits-your-stocks-bonds-gold-and-silver-investments-explained/4386888/
- South Korea’s KOSPI up 1.4%, Hang Seng edges higher as chip stocks recover. Can Anthropic’s debut revive the AI trade?, https://www.livemint.com/market/stock-market-news/south-koreas-kospi-up-1-4-hang-seng-edges-higher-as-chip-stocks-recover-can-anthropics-debut-revive-the-ai-trade-11795083814893.html
- Trump’s Tariff Refund Saved Lowe’s From An Earnings Miss. Here’s The Math On How Government Tariff Refunds Are Padding Retailers’ Profits, https://247wallst.com/investing/2026/11/20/trumps-tariff-refund-saved-lowes-from-an-earnings-miss-heres-the-math-on-how-government-tariff-refunds-are-padding-retailers-profits/
- Q3 2026 U.S. Retail Scorecard – Update November 19, 2026, https://lipperalpha.refinitiv.com/2026/11/q3-2026-u-s-retail-scorecard-update-november-19-2026/
- Treasury Yields Snapshot: November 20, 2026, https://www.advisorperspectives.com/dshort/updates/2026/11/20/treasury-yields-snapshot-november-20-2026
- Market Yield on U.S. Treasury Securities at 10-Year Constant, https://fred.stlouisfed.org/series/dgs10
- Euro Area Inflation Rate – Trading Economics, https://tradingeconomics.com/euro-area/inflation-cpi
- British Pound to Euro Forecast: GBP Retreats After Softer UK CPI, https://www.currencynews.co.uk/forecast/20261119-47803_british-pound-to-euro-forecast-gbp-retreats-after-softer-uk-cpi.html
- Consumer price inflation, UK: October 2026, https://www.ons.gov.uk/economy/inflationandpriceindices/bulletins/consumerpriceinflation/october2026
- Pound-to-Euro Forecast: Brexit Negotiation Setback Weighs on GBP/, https://www.currencynews.co.uk/forecast/20261120-47812_pound-to-euro-forecast-brexit-negotiation-setback-weighs-on-gbp.html
- Euro Steadies vs Pound as UK Inflation Misses Forecasts, https://www.tradingpedia.com/2026/11/19/euro-steadies-vs-pound-as-uk-inflation-misses-forecasts/
- Euro holds gains as the British Pound remains weighed down by undershot UK inflation, https://www.fxstreet.com/news/euro-holds-gains-as-the-british-pound-remains-weighed-down-by-undershot-uk-inflation-202611190729
- European shares tumble again as Anthropic debut fails to halt tech, https://au.investing.com/news/stock-market-news/european-shares-near-1month-lows-as-anthropics-debut-fails-to-halt-tech-rout-4785772
- AI selloff drives Taiwan stocks to worst week in 35 years, https://hedgeweek.com/news/ai-selloff-drives-taiwan-stocks-to-worst-week-in-35-years
- HK, mainland slip as tech stocks take brunt of fears – RTHK, https://gbcode.rthk.hk/TuniS/news.rthk.hk/rthk/en/component/k2/1878603-20261120.htm?spTabChangeable=0
- Hang Seng slumps nearly 400 points in early trade on Friday, tech, https://www.thestandard.com.hk/finance/article/349090/Hang-Seng-slumps-nearly-400-points-in-early-trade-on-Friday-tech-down-4-percent
- India’s Record-Breaking Performance: A Fresh Wave of Global, https://taxguru.in/finance/indias-record-breaking-performance-fresh-wave-global-investment-turns-india.html
- Taking Stock: Bulls tighten grip on D-Street; Sensex, Nifty gain for fourth straight week, https://www.tradingview.com/news/moneycontrol:ab7ef36a4094b:0-taking-stock-bulls-tighten-grip-on-d-street-sensex-nifty-gain-for-fourth-straight-week/
- NIFTY Bank at record high, Apollo Hospitals leads – Upstox, https://upstox.com/news/market-news/stocks/market-wrap-nov-20-nifty-50-ends-at-25-801-sensex-jumps-898-pts-nifty-bank-at-record-high-apollo-hospitals-leads/article-203784/
- Historical Index Data – NSE, https://www.nseindia.in/reports-indices-historical-index-data
- Indian Stock Market Today – Vittarthi Financial Calculators, https://vittarthi.com/markets/india
- Consumer Durables, Metals Lead Selloff; Pharma Outperforms, https://hdfcsky.com/news/sectoral-snapshot-today-november-18-2026-consumer-durables-metals-lead-losses-auto-it-also-drag
- Market Wrap: Nifty Jumps 286 Points as Sensex Gains Nearly 900, https://scanx.trade/stock-market-news/markets/market-today-closing-bell-update-nifty50-share-price-sensex-share-price-crude-fii-gift-nifty-rupee-latest-20-11-2026/56715153
- Stock Market Update 20 November 2026: Sensex, Nifty 50 Trade in, https://www.kotakneo.com/news/market-news/stock-market-update-20-november-2026-sensex-nifty/
- Stock Market Today Highlights: BSE Sensex closes above 83,900, Nifty50 tops 25,800, https://timesofindia.indiatimes.com/business/india-business/sensex-stock-market-today-20-november-2026-live-updates-nse-bse-gift-nifty-50-top-gainers-losers-mcx-stocks-in-focus-market-news/liveblog/136011501.cms
- Indian Rupee hits fresh seven-month high against US Dollar – Mitrade, https://www.mitrade.com/au/insights/news/live-news/article-1-2267129-20261120
- FII DII Data Today (20 Nov) – Quantsapp, https://www.quantsapp.com/fii-dii
- Live FII & DII Trading Activity Daily, Monthly & Yearly – Groww, https://groww.in/fii-dii-data
- Closing Bell, 20 November 2026: Sensex, Nifty End Higher as, https://www.kotakneo.com/news/market-news/closing-bell-20-november-2026-sensex-nifty-rally-on-banking-it-stocks-and-fii-buying/
- Banking, IT, Healthcare Stocks Lead Market Rally Higher, https://hdfcsky.com/news/sectoral-snapshot-today-november-20-2026-banking-it-healthcare-lead-d-street-rally-metals-media-decline
- All Indices – Comprehensive List of Stock Market Indexes – Groww, https://groww.in/indices
- IndexPE | Track 140+ Indian Indices: Current Valuations & PE Analysis, https://indexpe.in/
- Free Live NSE Stock Charts: 140+ Indicators, 10-Year History, https://www.alphave.in/chart
- Indian Stock Market News, Equity Market and Sensex Today in India, https://www.equitymaster.com/tm/tm.asp?date=11/20/2026&title=Sensex-Today-Rallies-898-Points–Nifty-Above-25800–2-Reasons-Why-Indian-Share-Markets-Are-Rising
- Share Market Today: Live Stock Market, Sensex & Nifty – HDFC Sky, https://hdfcsky.com/markets
- Sensex, Nifty open flat amid Fed rate hike concerns; investors remain cautious, https://www.aninews.in/news/business/sensex-nifty-open-flat-amid-fed-rate-hike-concerns-investors-remain-cautious20261119094209
- NIFTY Midcap 100 Historical Data (NIFMDCP100) – Investing.com, https://www.investing.com/indices/cnx-midcap-historical-data
- Nifty Midcap 100 – Gift Nifty, https://giftnifty.org/nifty-midcap-100/
- Nifty Week Ahead 16–20 Nov 2026 | Riddhi Siddhi Share Brokers, https://www.riddhisiddhisharebrokers.com/nifty-week-ahead-16-20-november-2026
- Upper & Lower Circuit Stocks Today, November 20, 2026 at 3:30 PM, https://hdfcsky.com/news/upper-lower-circuit-stocks-november-20-2026-at-3-30-pm
- Latest Stocks, Equity, Nifty, Share Market News, NSE/BSE … – Upstox, https://upstox.com/news/market-news/
- Indian Rupee – Quote – Chart – Historical Data – News, https://tradingeconomics.com/india/currency
- Missed Diwali Week? Nifty Weekly Review Nov 9-13, 2026, https://getbelong.com/blog/weekly-review/nov9-13-analysis/
- India’s core infrastructure output hits new-series high of 10.9% in, https://infra.economictimes.indiatimes.com/news/urban-infrastructure/indias-core-infrastructure-output-hits-new-series-high-of-10-9-in-october/136031267
- Core sector growth hits 13-month high of 10.9% in October: Is India’s industrial recovery gaining momentum?, https://www.businesstoday.in/latest/economy/story/core-sector-growth-hits-13-month-high-of-10-9-in-october-is-indias-industrial-recovery-gaining-momentum-568806-2026-11-20
- Rising Wholesale Inflation in October 2026, Driven by Sharp, https://www.phdcci.in/2026/11/17/rising-wholesale-inflation-in-october-2026-driven-by-sharp-increase-in-fuel-and-power-prices-phdcci/
- WPI inflation hits series high of 12.29% in October on fuel, power costs, https://www.newindianexpress.com/business/2026/Nov/16/wpi-inflation-hits-series-high-of-1229-in-october-on-fuel-power-costs
- WPI Inflation October 2026: Wholesale Inflation Rises to 12.29% as, https://chartforest.com/wpi-inflation-october-2026/
- RBI’s second battlefront: How oil shock cost hits household kitchens, https://www.indiatoday.in/india-today-insight/story/rbis-second-battlefront-how-oil-shock-cost-hits-household-kitchens-3040980-2026-11-17
- India Inflation Rate – Trading Economics, https://tradingeconomics.com/india/inflation-cpi
- Weekly policy watch: PM Modi’s Asean visit and WPI inflation in focus, https://www.business-standard.com/economy/news/modi-philippines-asean-summit-wpi-inflation-unemployment-forex-reserve-126111600783_1.html
- Brent oil – Price – Chart – Historical Data – News – Trading Economics, https://tradingeconomics.com/commodity/brent-crude-oil
- Rupee climbs above 93 against US dollar for first time since April, https://www.babushahi.com/business.php?id=230102
- India’s WPI Inflation Hits 12.29% in October 2026 – CapitalVia, https://www.capitalvia.com/insights/india-wpi-inflation/
- Core infrastructure output growth hits 31-month high of 10.9% in, https://www.livemint.com/news/core-infra-sector-growth-hits-a-series-peak-peak-of-10-9-likely-to-lift-october-industrial-output-expansion-11795183928698.html
- Upcoming IPOs – Screener, https://www.screener.in/ipo/
- IPO Subscription Status Today – Live BSE and NSE Data, https://www.ipoplatform.com/ipo/subscription-status
- Current & New IPOs in 2026 – Mint, https://www.livemint.com/market/ipo
- Japan Stocks Suffer 3000-Point Crash as AI Selloff Deepens, https://newsonjapan.com/article/151462.php
- NASDAQ drops 1.4%, S&P 500 dips 0.4% hitting 8-month low – Upstox, https://upstox.com/news/market-news/us-stocks/wall-street-extends-fall-nasdaq-drops-1-4-s-and-p-500-dips-0-4-hitting-8-month-low/article-203795/
- Red Friday as Asia’s AI trade unravels – investingLive, https://investinglive.com/news/investinglive-asia-pacific-market-news-red-friday-as-asia-s-ai-trade-unravels/
- Asian Markets Crash: Nikkei and KOSPI Fall 5%, SoftBank 14%, https://aibubblemonitor.com/news/asian-markets-crash-nikkei-kospi-softbank-ai-selloff
- Nikkei Stock Average, Nikkei 225 (NIKKEI225) | FRED | St. Louis Fed, https://fred.stlouisfed.org/series/nikkei225
- TOPIX INDEX TODAY | LIVE TICKER | TOPIX QUOTE & CHART, https://markets.businessinsider.com/index/topix
- Kospi Terbang 2,9%, Bursa Asia Pesta Efek Kinerja Nvidia, https://www.cnbcindonesia.com/market/20261118073604-17-786125/kospi-terbang-29-bursa-asia-pesta-efek-kinerja-nvidia
- Japan Stocks Face Volatile Week After Historic Selloff, https://newsonjapan.com/article/151291.php
- Japan GDP Q3 2026: Yen Near 160 and the BoJ December Call, https://admiralmarkets.com/analytics/traders-blog/japan-gdp-q3-2026-yen-usdjpy-160
- Japan Stock Market Index (JP225) – Quote – Chart – Historical Data, https://tradingeconomics.com/japan/stock-market
- Japan’s October core CPI rises to 2.2%, misses estimates, and, https://www.tradingview.com/news/seekingalpha:5e0a69e09094b:0-japan-s-october-core-cpi-rises-to-2-2-misses-estimates-and-headline-inflation-hits-11-month-high/
- Commodities: Sentiment Hangs on Tech; China is the Driver, https://daily.fattail.com.au/commodities-sentiment-hangs-on-tech-china-is-the-driver/20261120/
- Stock investors are giving up on China – The Hill, https://thehill.com/opinion/international/6231063-xi-economic-plans-failing/
- Shanghai Shenzhen CSI 300 Index | Live Quote | Historical Chart, https://tradingeconomics.com/shsz300:ind
- Evening Wrap: ASX 200 falls on major breakdowns in iron ore, https://www.marketindex.com.au/news/evening-wrap-asx-200-falls-on-major-breakdowns-in-iron-ore-copper-and-lithium
- China Holds LPR Rates at Record Lows for 18th Month, https://tradingeconomics.com/china/interest-rate/news/602908
- China Loan Prime Rate – Trading Economics, https://tradingeconomics.com/china/interest-rate
- Hong Kong stocks fall 20% from 2026 high as AI selloff spreads, https://www.hindustantimes.com/business/hong-kong-stocks-fall-20-from-2026-high-as-ai-selloff-spreads-101795160799234.html
- Weekly Hang Seng TECH Index Options – HKEX, https://www.hkex.com.hk/Products/Listed-Derivatives/Equity-Index/Hang-Seng-TECH-Index-Futures-and-Options/Weekly-Hang-Seng-TECH-Index-Options?sc_lang=en
- Hang Seng Index drops 500 points to 18-month low as tech shares, https://www.dimsumdaily.hk/hang-seng-index-drops-500-points-to-18-month-low-as-tech-shares-tumble/
- CATL and Hesai added to Hong Kong’s Hang Seng Tech Index as, https://cnevpost.com/2026/11/20/catl-hesai-added-hk-hang-seng-tech-index/
- Hang Seng Tech Index Expands to 50 Constituents for First Time, Adding CATL and 19 Others in One Sweep, https://finance.biggo.com/news/47f51608-f789-45e4-90dd-3f9bb71b0e6f
- Hang Seng Tech Index expands to 50 stocks, adding CATL and, https://mlq.ai/news/hang-seng-tech-index-expands-to-50-stocks-adding-catl-and-luxshare/
- ASX 200 Live Today – Friday, 20th November, https://www.marketindex.com.au/news/asx-200-live-today-friday-20th-novemeber
- ASX 200 Below 9,000: Four-Day Losing Streak Turns Month Red, https://thebull.com.au/news/asx-200-below-9000-four-day-losing-streak-turns-month-red/
- ASX 200 volatile as unemployment rises to a 5-year … – Motley Fool, https://www.fool.com.au/2026/11/19/asx-200-volatile-as-unemployment-rises-to-a-5-year-high-dampening-rate-hike-fears/
- BHP share price drops 13% to seven-month low in just 1 week. Do experts say buy?, https://www.fool.com.au/2026/11/20/bhp-share-price-drops-13-to-seven-month-low-in-just-1-week-do-experts-say-buy/
- Iron Ore Slips Below $90 a Tonne: BHP (ASX:BHP) and Fortescue, https://kalkine.com.au/news/commodities/iron-ore-slips-below-90-a-tonne-bhp-asxbhp-and-fortescue-asxfmg-face-the-pilbara-squeeze
- Australia’s Wage Growth Hits 1.1%: What Does the RBA’s 4.85% Cash Rate Mean for ASX 200 Investors?, https://kalkine.com.au/news/financial/australias-wage-growth-hits-11-what-does-the-rbas-485-cash-rate-mean-for-asx-200-investors
- NZX 50 Ends Little Changed, Holds at Record High, https://tradingeconomics.com/new-zealand/stock-market/news/601794
- NZX 50 dips as A2 Milk slides on souring outlook – NBR, https://www.nbr.co.nz/market-close/nzx-50-dips-as-a2-milk-slides-on-souring-outlook/
- New Zealand Interest Rate – Trading Economics, https://tradingeconomics.com/new-zealand/interest-rate
- NZ 5-Year Inflation Expectations Fall to 2.17% – Briefs Finance, https://www.briefs.co/news/new-zealand-s-long-term-inflation-expectations-dip-as-near-t/
- NZ 1-year inflation expectations jump to 2.9%, but the 2-year anchor, https://investinglive.com/central-banks/nz-1-year-inflation-expectations-jump-to-2-9-but-the-2-year-anchor-barely-moves/
- RBNZ Governor concerned higher fuel costs may be feeding into, https://www.interest.co.nz/economy/141150/reserve-bank-governor-anna-breman-says-indirect-impact-elevated-fuel-prices-may-be
- Asia’s stock markets dive as Anthropic debut fails to allay AI bubble fears, https://www.aljazeera.com/economy/2026/11/20/asias-stock-markets-dive-as-anthropic-debut-fails-to-allay-ai-bubble-fears